

1. Notes from the First Session
Tuesday, 1:40 p.m. The main lecture hall in the graduate business school's main building.
The plant manager sat in the front row and opened his notebook to the first page. Beneath the date marked 'Sixth Class,' the letter B was circled beside A.
Next to it were the words he had spoken into the microphone.
'No company leaves people and machines sitting idle. Standard products do move eventually.'
Beneath that sentence were the product manufacturing costs per unit, 30 and 21, followed by net profit, 1,500 and 2,400. That day, he had looked first at B's production volume, then, once the calculations were done, at net profit. Both numbers had supported his choice.
On the next page were the tables for variable costing and throughput accounting. The page after that held the changes in cash calculated the previous week. He had drawn a double underline beside B's −16,500.
The plant manager returned to the first page. The sentence 'Standard products do move eventually' specified neither when they would sell nor who would buy them. Until last week, he had taken it as a statement about the nature of the product. Reading it now, he saw that it justified production on the assumption of sales that had not yet happened.
The production manager set down his bag in the next seat and asked a question.
"Did you do last week's homework? Who should get the bonus?"
"I've written down an answer."
"So have I. But I don't know whether I could give the same answer at work."
The plant manager looked at him. His notebook was open, but he had not picked up his pen.
Participants came in along the aisles. The sales executive and the owner of a small business sat in the middle rows, while the cost accountant was showing the finance manager a passage in last week's notes. In the very last row, the fellow professor was looking toward the lectern.
The plant manager kept the first page open. Today was the ninth class.
2. A Second Vote
As soon as he reached the lectern, the professor switched on the screen. It showed the table they had seen at the end of last week's class.
| Company A | Company B | |
|---|---|---|
| Financial accounting: net profit | 1,500 | 2,400 |
| Variable costing: net profit | 1,500 | 1,500 |
| Throughput accounting: net profit | 1,500 | −5,700 |
| Change in cash | +1,500 | −16,500 |
| Ending finished goods quantity | 0 | 900 |
"Last week, I asked you to take your own answer home. I also asked you to write down which figures you had used to decide. Today, we will begin with those answers."
The professor wrote A and B on one side of the board, then the results of the first vote beneath them. Sixty and forty.
"In our first session, sixty of you chose A and forty chose B. In the two classes that followed, we deferred the final choice. Now we will vote again on the same question. If you were the group chair, which CEO would you give the bonus to?"
The plant manager laid his pen on his notebook.
"Please raise your hand if you would give the bonus to Company A's CEO."
In the front row, the plant manager raised his hand. The production manager beside him did too. Hands went up through the middle rows to the very back. The teaching assistant walked along the aisle, checking the seats.
"Ninety-seven."
The professor asked them to lower their hands, then asked about B. Three people raised their hands.
The teaching assistant checked the seats again.
"Three."
The second result went onto the board. A 97, B 3.
No one laughed or turned to a neighbor as they had in the first session. The plant manager lowered his arm and looked at the circle on the first page.
"The choices have swung strongly to one side," the professor said. "But the fact that a majority has given the same answer does not establish the validity of a business judgment. Today, we will examine the grounds for that judgment. In particular, I would like to hear from those who chose B in the first session."
3. The Reasons of the Forty
The production manager took the microphone first.
"At first, I called it cost reduction because the more units you make, the less fixed cost each unit carries. The calculated product cost did fall. But they hadn't used less material or less electricity. Both companies paid the same factory fixed costs, too. I've changed my judgment that this was an achievement in cost reduction."
The professor nodded and looked at another participant. He did not put up a new calculation table.
The cost accountant raised his hand.
"Last week, I said it was not cash until it came back. I revisited the homework with that thought in mind. I still think it is correct to describe inventory as an asset. The problem was that I went from that description to the conclusion that B deserved the bonus. How we record inventory and whether we recognize making more as an achievement are different judgments."
Without closing his notebook, he passed the microphone to the next person.
From the back, the graduate student who had said in the first session that his choice of B was half based on instinct spoke up.
"I chose B because I felt B had done more work. At first, I thought A needed to explain why it had produced so little. Now I think B needs to explain why it made another 900 units with the same sales volume."
The plant manager in the front row turned his head. The graduate student spoke without looking at his laptop screen.
"I think I counted the extra units as an achievement first, then went looking for a reason."
The fellow professor took the microphone in the last row.
"In the seventh class, I explained the intention behind my initial choice. I wanted to show that accepting net profit as the criterion for performance evaluation leads us to choose B. In making this choice, we must examine the suitability of that criterion itself. The fact that B's net profit under absorption costing is higher does not, on its own, justify judging B's business decision to have been superior."
The professor looked at the plant manager.
"And how did you see it?"
"I gave them credit for not leaving people and machines idle. Even now, I don't think the people who worked hard on the shop floor to do that lacked diligence. But that reason alone isn't enough for me to say B did more for the company."
He put his finger beneath the sentence on the first page.
"In the first session, when you asked whether I thought it would all sell, I said I couldn't guarantee it. Then I added that it would move eventually. I used sales I wasn't certain of myself as grounds for continuing production."
In the middle rows, the sales executive nodded. This time, it was not his turn to argue back.
From the aisle beside him, the head of production raised his hand. He was one of the three who had chosen B.
"At our company, supply can't keep up with demand right now. Everything we make sells. I chose B again today because I was thinking of our own situation, where we have to keep producing quickly. If we were using make-to-stock production like Company A, with supply exceeding demand, I would choose A too."
The head of construction at a construction company took the microphone.
"We have to keep moving quickly as well. The project is confirmed, and we have to meet the delivery schedule. If we leave people and equipment idle when the work is already secured, completion will be delayed. That experience is why I chose B. If we were producing to stock beyond demand, I would choose A too."
Finally, a production director at a make-to-order company spoke.
"We manufacture against orders with confirmed sales. We have to make and deliver the quantities ordered quickly. That was why I raised my hand for B as well. But if we were making to stock like Company A, with supply exceeding demand, I would choose A."
The professor listened to all three before replying.
"When sales are secured, or when a confirmed construction project has a delivery schedule to meet, rapid production is a sound decision. Your companies have secured the demand that justifies that production. In contrast, there was no evidence of additional sales for B in this case."
4. The Professor's Verdict
The professor walked to the board. Standing between the first and second votes, he spoke.
"In this case, I would give the bonus to Company A's CEO."
The plant manager turned his gaze to the professor. It was the first time the professor had given his own verdict on the question they had heard several times since the first session.
"My grounds are the sales performance of the two companies, and the production and funds committed to achieve it. Both sold 100 units, with revenue of 5,000. A produced the 100 units corresponding to those sales. B produced 1,000 units, but made no additional sales. Nor does this case provide evidence supporting additional sales of the excess production."
The professor pointed to the ending finished goods quantity on the screen.
"B paid additional materials costs and variable overhead for 900 unsold units. That is 900 multiplied by 20 per unit, or 18,000. A achieved the same sales performance without committing those additional funds. Examining production volume alongside the change in cash makes the difference between the two managers' decisions clear."
The business owner took the microphone.
"That was what I asked on the first day. They hadn't sold any more, so could we say they'd earned that much more just because net profit was 900 higher?"
"We can now add a verdict to that question. Under absorption costing in this case, 900 of B's 1,000 in fixed manufacturing costs was carried in ending inventory. At A, the full 1,000 in fixed manufacturing costs was included in cost of goods sold. That difference in expense recognition is why B's net profit for the period was calculated to be 900 higher than A's. The profit difference did not arise from greater sales performance."
The professor looked at the business owner.
"May I ask you something? When you founded your company, did you do so to make net profit larger?"
The business owner thought for a moment before answering.
"I founded it to make money. Net profit was a number I looked at to check that."
"On that basis, B in this case did not earn more money either. It was no different from sacrificing hard-earned cash in hand for a future in which sales were uncertain."
The professor pointed to the three net-profit rows on the screen in turn.
"The same Company B, over the same period, can show 2,400, 1,500, or −5,700, depending on the calculation method. Over that period, B's cash fell by 16,500. Net profit is an opinion, one that varies with the costing method and the choices made in valuation. A net profit of 10 billion won does not mean the company has earned 10 billion won in money. The distance between accounting profit and money actually earned is as wide as the Pacific Ocean."
The professor moved his hand to the change-in-cash row.
"Let me clarify one point. In this course, I have been using the word cash. But what I mean, precisely, is money. Cash and money are different. Money is a broader concept than cash; cash assets are not the only form of money. The money a company earns does not simply accumulate as cash in a vault. It may become bank deposits, real estate, or other forms of assets. There is, however, a condition. The asset must be able to serve as purchasing power at an appropriate value, or be put to another use, when wanted. To be money, it must be usable like cash. An asset that is tied up when needed cannot be called money. In that respect, the funds B paid for its unsold inventory have not yet passed through sale and collection to return as cash."
The professor took his hand away from the screen.
"If we recognize that 900 as additional business performance and award a bonus, we reward the decision to build inventory without evidence of additional sales. I do not judge that decision to be better than A's choice."
The cost accountant asked a question.
"Does that mean we should judge a company with inventory to have done worse than one without it?"
"We cannot generalize in that way. Inventory is necessary. Inventory consists of assets held for sale and is a source of future earnings. Without inventory, a manufacturing company cannot generate future sales. The question is the appropriate level. Where demand and delivery schedules are secured, as at the three companies we have just heard from, production should meet those requirements. We cannot judge a company to have incurred a loss simply because it holds inventory, or to have performed well simply because it reduced production. In today's comparison, we held the other conditions equal, and there is no evidence of sales to justify B's additional production. Under those conditions, B's 900 units are inventory beyond an appropriate level."
"So A isn't the answer simply because its cash increased more, either," the finance manager said.
"The change in cash is important evidence to examine. But a greater increase in cash over one period cannot, by itself, determine the relative merits of every business decision. A company must commit funds to future production and sales. In reaching this verdict, we considered both the additional funds B committed for the same sales performance and the grounds for recovering those funds."
The professor pointed again to the ending finished goods quantity on the screen.
"The 18,000 B paid for its 900 unsold units is tied up in working capital in the form of inventory. This is not a problem unique to this case. In today's world economy, many companies tie up large sums for long periods in working capital beyond appropriate levels, particularly in inventory. Companies whose inventory values are persistently high inevitably have surplus and obsolete inventory. Working capital is part of invested capital. By selling or disposing of inventory beyond their needs and reducing unnecessary additional production and purchasing, companies can recover the funds tied up in working capital as cash. That is why managing working capital at an appropriate level has become a common challenge for companies in many countries."
The production manager took the microphone. This time, he addressed the lectern with what he had said to the plant manager before class.
"I chose A here too. But at work, if production makes less, the first thing we have to do is explain the fall in utilization. If I take today's answer back as it stands, it will sound as though I'm saying I want to do less work."
The fellow professor replied.
"If the performance criteria stay the same, managers will still be required to make decisions that meet those criteria. Agreeing with the conclusion of this case must be distinguished from changing an organization's evaluation system. Today's second vote does not resolve that problem of implementation, either."
The professor looked at A 97 on the board.
"That is why you must continue examining how evaluation and rewards work in your companies. But I will not defer today's verdict because implementation is difficult. In this case, the manager who deserves the bonus is A."
The plant manager wrote A in his notebook. He now knew what reasons he would write beside it.
5. The Plant Manager's Choice
Even after class ended, the plant manager kept his notebook open.
'The same sales. Another 900 units produced without evidence of additional sales. An extra 18,000 paid in cash.'
Beside him, the production manager picked up his bag.
"What will you do when you go back?"
The plant manager paused his pen.
"Choosing A today doesn't mean I can stop my factory's line tomorrow. First, I need to check what sales are planned at our plant, and how much of what we're producing now is needed for them. Company A here and my factory aren't the same company."
"That's right."
There was no reason to reject the diligence that had sustained his fifteen-year principle: The line never stops. But judging performance required examining the sales and recovery of funds that followed the running of the equipment.
"Still, I need to rethink calling something well done just because we made more. That was precisely why I praised B on the first day."
The production manager looked at the plant manager's notebook and nodded. Then he stepped into the aisle.
The plant manager did not erase the B on the first page. He wanted to preserve what he had looked at when making his judgment that day. More units produced on the same equipment, a lower calculated unit cost, and higher net profit. None of those figures had been his invention. The error had been to conclude his performance evaluation with those numbers alone.
Beside A, he wrote one more sentence.
'Achieved the same sales performance while avoiding additional production and the commitment of funds without supporting evidence.'
The net profit of 2,400 that had made him sit a little straighter in the first session was still on the page. Beside it now were the grounds for his judgment, written in his own hand.
The plant manager closed his notebook. At the lectern, the teaching assistant was switching off the screen. On the board were sixty and forty from the first vote, with today's ninety-seven and three beside them.
Epilogue
This fiction began with a course EXA taught more than twenty years ago for practitioners sent by their companies. About forty participants were presented with the situations of A and B and asked which of the two managers should receive a bonus. The calculations and their implications had not yet been explained.
About 60% chose A and about 40% chose B. EXA was surprised that more people than expected had chosen B. After working through the calculations for the same case and explaining their implications, EXA asked them to choose again. Everyone who had initially chosen B changed their judgment to A.
The classroom of a hundred people and the characters' dialogue in this story are fiction constructed from that experience. What the actual course revealed was that, even when looking at the same situation, judgments of performance differed depending on whether people focused on production volume, calculated costs, or accounting profit. The calculations made it possible to examine the grounds for those judgments.
In the comparison between A and B, A receives the bonus. Both companies achieved the same sales performance, and A avoided production and the commitment of funds unsupported by evidence of additional sales. B's higher accounting profit could not serve as evidence that the additional production was superior. That is why we examined three costing methods alongside cash flow before reaching this conclusion. Among these, a cash-flow framework based on Free Cash Flow is central to financial decision-making. This series will take up that framework as one of its core subjects.
More than twenty years have passed since that course, but the situation in companies today is not greatly different. Outside the classroom, the conditions surrounding sales and production are more complex, and managers act according to the criteria their organizations use to evaluate them. When the fictional participants return to their companies, those companies' performance criteria are unchanged. The fictional production manager's hesitation over whether he could give the same answer back at work shows that the problem of implementation continues even after the calculations are understood.
How does your company currently evaluate choices like B's? In what direction is that evaluation steering next month's production?
Next Episode
The course continues. If net profit does not show the money earned, which number should we look at to assess a company's ability to make money? The next class begins by asking whether that ability is under threat.
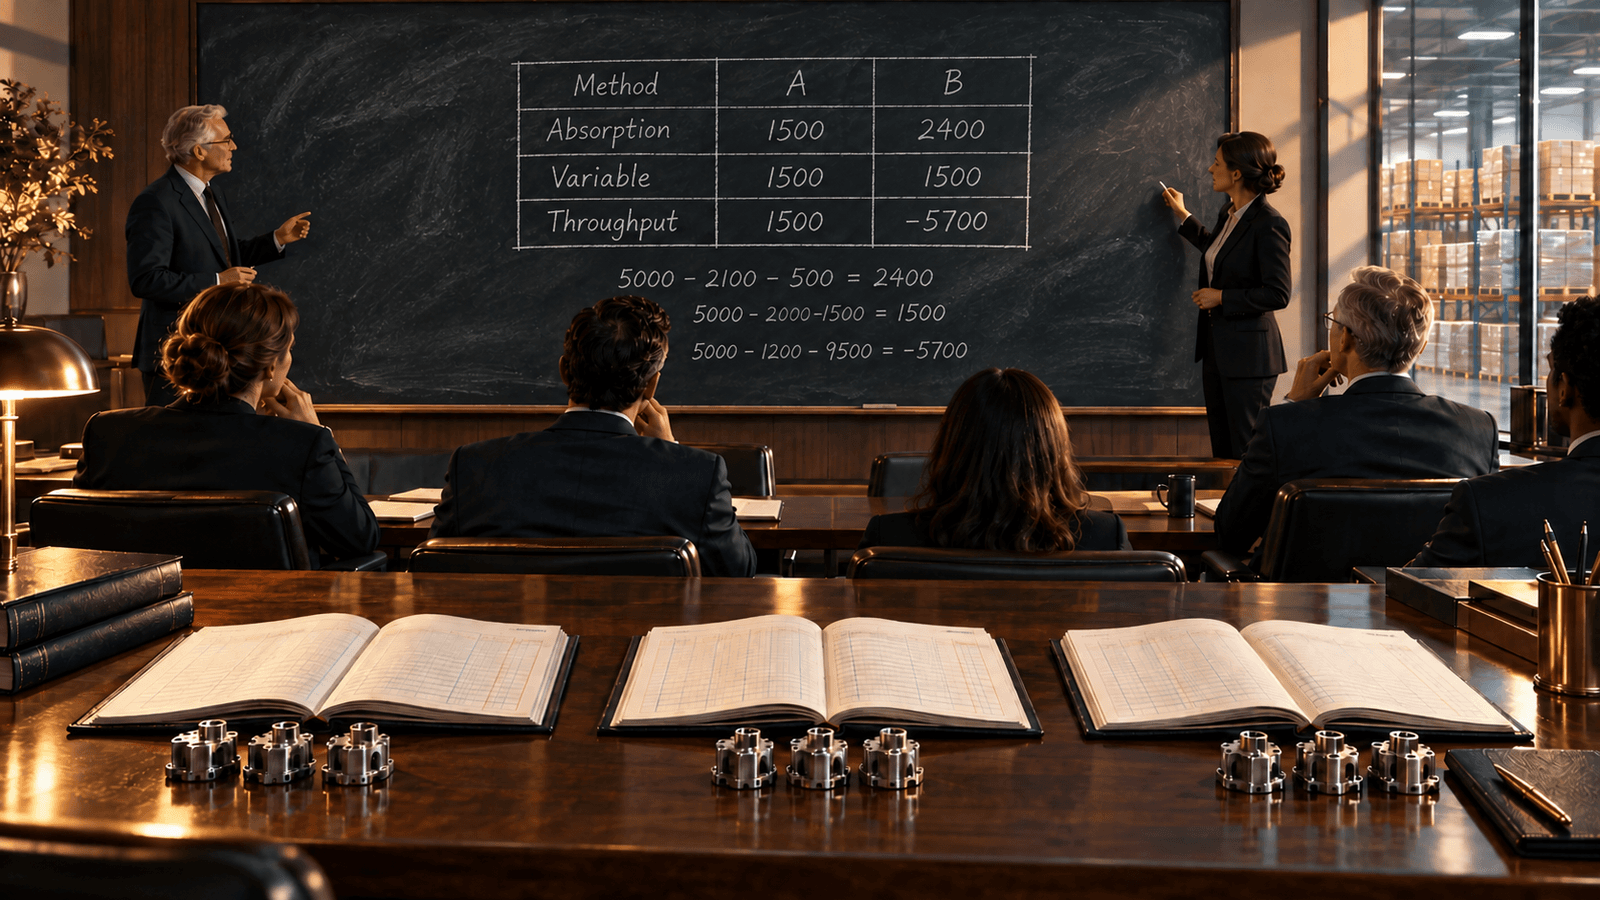
Join the discussion